Winning a Bidding War on a Long Island Home Without Overpaying
Redfin’s June 23 report on spring competition placed a Long Island county near the top of a national list. In May, 51.6% of the homes that sold in Nassau County closed above their original asking price, a gain of 3.3 percentage points from a year earlier and the fourth-highest share among the 50 most populous metros Redfin ranked. Nationwide, the figure was 25.8%, the lowest May reading since 2020.
Suffolk County shows the same pressure through a different measure. OneKey MLS data for August, reported by Long Island Guide, put the median share of original list price received at 102.2% in Suffolk (101.3% a year earlier) and 100.5% in Nassau (100.1%), with median days on market at 39 and 38. The two statistics do not measure the same thing, since one counts how many homes sold above asking and the other tracks a median price ratio, but both describe a market where a first offer at the list price often loses.
The timing adds a cost. Freddie Mac’s weekly average for a 30-year fixed mortgage stood at 7.40% on October 8, against 6.30% a year earlier, which is covered in Mortgage Rates Reach 7.40%. Every dollar of overbid now carries a higher monthly price than it did last fall. What follows covers how a Long Island offer becomes a binding contract, what a seller’s side tends to weigh, what an overbid does to a payment, and which moves are worth their price.
How a Long Island offer becomes a contract
The bidding happens before anything binding exists. According to Nolo’s guide to New York purchases, an offer is usually made on a short form supplied by the listing broker, acceptance can be communicated orally, and neither side is bound until both sign a formal contract of sale, which typically happens at least a week after the seller accepts. Attorneys for both sides prepare and negotiate that contract.
Two figures matter for a buyer who is about to compete. The contract deposit is typically 10% of the purchase price, paid at signing and held in an attorney escrow account, and a buyer who cancels without a reason the contract recognizes may lose it as liquidated damages. On the $760,000 Suffolk median from August, a 10% deposit is $76,000. The national guides that circulate in bidding-war articles often put earnest money at 1% to 3%; that range does not describe how Long Island contracts are usually funded, so any advice built on it needs translating. Nolo’s article was last updated in August 2023, so a buyer’s own attorney should confirm current practice.
What a seller’s side reads first
The Close, which published its list of bidding-war tactics in 2024 and updated it in June 2025, notes that bidding wars tend to form when several offers land within 24 to 36 hours of a listing going live. In that window, the offers get compared side by side. The table below sorts the usual levers by what each one signals and what it can cost the buyer.
| Lever | What it signals to the seller | What it can cost the buyer |
|---|---|---|
| Price above ask | Willingness to pay | Monthly payment, cash at closing, appraisal risk |
| Several preapproval letters | The financing is real | Time spent with lenders |
| Attorney lined up before the offer | The contract will come back fast | Retainer paid before knowing the outcome |
| Larger deposit | Commitment | Cash tied up in escrow; exposure if the deal fails |
| Fewer contingencies | Certainty of closing | The deposit, if the buyer cannot close |
| Appraisal gap coverage | The price will survive a low appraisal | Cash the buyer may have to produce |
| Closing date or rent-back flexibility | The seller’s next move gets easier | Buyer’s own housing logistics |
| Escalation clause | Automatic outbidding up to a ceiling | A final price the buyer sets in advance |
Moves that cost little
Preapproval comes first, and SoFi’s April 2026 guide notes that many experts recommend collecting letters from at least three lenders, not one. A letter shows a listing agent that the buyer has been vetted, and holding several also leaves the buyer a choice if one lender’s pricing changes before contract.
Finding out what the seller needs is the next step. The Close advises asking the listing agent which term matters most to the seller, such as a closing window that fits their next purchase. A rent-back, in which the buyer lets the seller stay for a few weeks at little or no rent after closing, is a version of the same idea, and The Close lists it among its tactics.
An attorney who is already retained matters more on Long Island than in states where agents handle the paperwork, because the contract is drafted and negotiated by lawyers. A buyer who has someone ready to turn a draft around the same day removes a source of delay that a seller may weigh. This point is an observation drawn from how the process works, not a statistic.
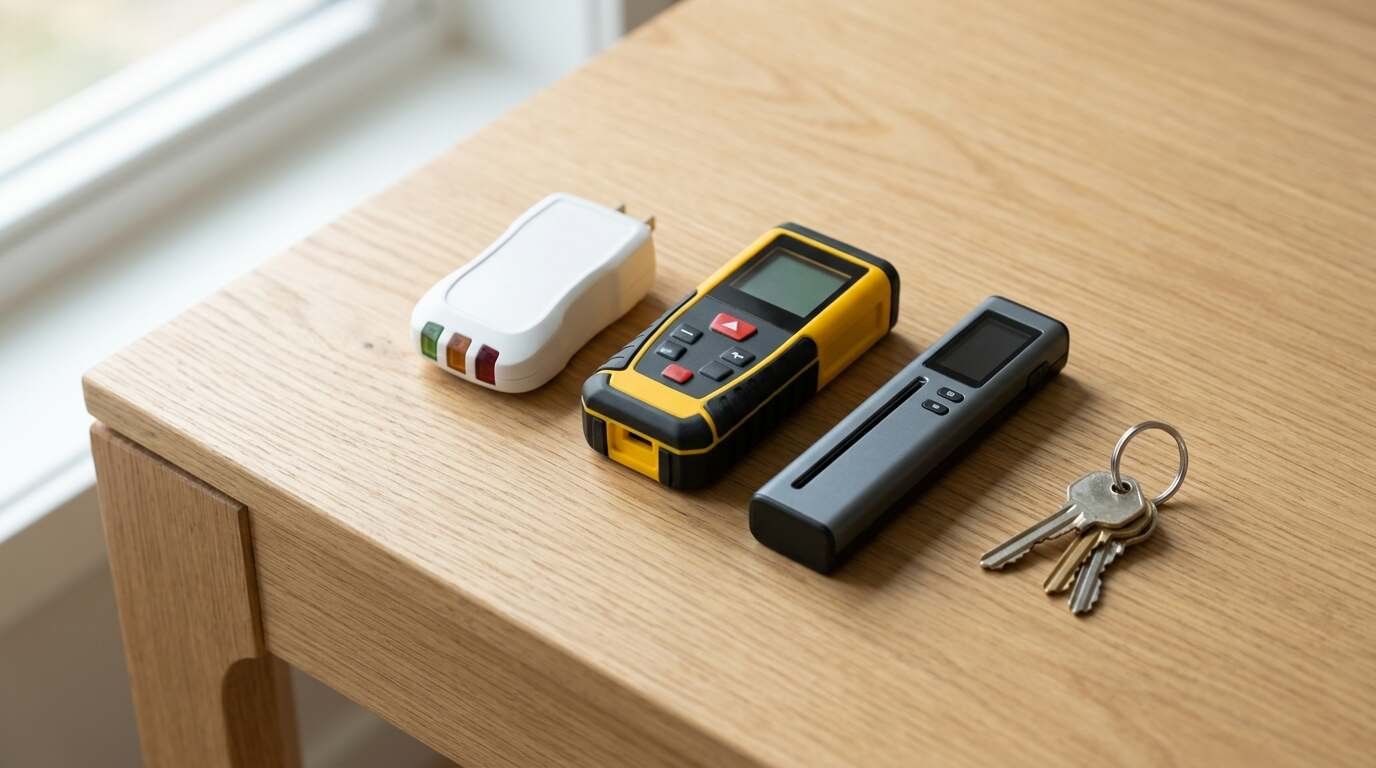
Documents also need to move quickly: proof of funds, preapproval letters, and signed forms. A portable scanner and a few minutes of preparation help, and the tools section below includes one.
Moves that cost real money
Price is the obvious lever and the easiest to overuse. The Close points out that $5,000 on a $250,000 home is 2%, while 10% over on a $400,000 home is $40,000, which is a reminder to think in percentages and in monthly payments. The next table uses the August Suffolk median of $760,000, a 20% down payment, and the 7.40% rate, and shows principal and interest only on a 30-year fixed loan. The figures are standard amortization arithmetic and do not include taxes, insurance or mortgage insurance.
| Offer | Loan (20% down) | Monthly principal and interest | Added per month | Added cash at closing |
|---|---|---|---|---|
| $760,000 | $608,000 | $4,210 | none | none |
| $780,000 (+$20,000) | $624,000 | $4,320 | $111 | $4,000 |
| $800,000 (+$40,000) | $640,000 | $4,431 | $222 | $8,000 |
At that rate, $40,000 over asking adds about $2,659 a year in interest and principal payments, plus $8,000 more at the table if the down payment stays at 20%. The bigger risk sits elsewhere. A lender generally bases the loan on the lower of the price and the appraised value, so a house that appraises under a competitive price leaves the buyer to cover the difference. That is the situation an appraisal gap clause addresses, and The Appraisal Gap Addendum Is a Negotiating Instrument explains how to cap the exposure.
Contingencies come next. The Close says a buyer who waives the financing contingency levels the field with cash buyers, and SoFi cautions that waiving contingencies can cost the earnest money if something goes wrong. In New York, a mortgage commitment contingency is the clause that lets a buyer exit without losing the deposit when financing fails, per Nolo. Giving it up while the deposit is 10% turns a lender’s decision into the buyer’s risk. The Inspection Contingency Is Not a Formality covers the inspection side, and The Contingency Removal Deadline Is a Hard Stop covers what happens when a deadline passes.
Inspection timing is its own pressure point. Nolo advises inspecting a property before signing the contract in New York, which compresses the schedule when several offers are due. Some buyers pay for an inspection before bidding, accepting the fee even if the offer loses. Others shorten the window. Either way, the home inspection report becomes a negotiating document later, as The Inspection Report as a Negotiating Document describes.
An escalation clause automates the outbidding. SoFi’s example is a $400,000 offer with a $10,000 increment and a $430,000 ceiling: if a competing bid reaches $410,000, the offer rises to $420,000. The Close’s author says such clauses worked about half the time, which is an anecdote and not a measured rate. Whether a seller’s side will accept one, and what proof of a competing bid they will want, is a question for the buyer’s attorney.
A move to skip
The personal letter to the seller is a staple of older bidding-war advice, and it carries fair housing risk. NAR’s reporting on buyer letters explains that they can reveal information about race, religion, national origin or familial status, and that a seller who accepts or rejects an offer on that basis may violate fair housing law even without intending to. Alexia Smokler, NAR’s director of fair housing policy, said in February 2023 that “the seller could be violating the law.” Oregon passed the first state ban on the letters in July 2021, and a federal court struck it down in March 2022, so the risk rests on the Fair Housing Act and state and local laws, not on a ban in New York.
Barbara Corcoran, in a May 2023 article carried by the Daily Press Tribune, put the alternative in one line: you have to “look like the best deal in town”. The financial terms, not the biography, carry that weight.
Where to stop
A ceiling set before the first showing is the only protection against a bidding room’s momentum. The behavioral research on why buyers overpay is covered in The Science of Why We Overpay for Houses. A practical ceiling combines three numbers: the monthly payment that still fits the budget at today’s rate, the cash available after the deposit and closing costs (see What Closing Costs Actually Look Like on Long Island), and an insurance quote obtained before the offer, as The Insurance Quote Comes Before the Offer recommends.
Losing a house at the ceiling is an outcome, not a failure. Sellers in this market receive offers they can compare line by line, and the winner is whoever fits the seller’s terms, which is not always the highest bidder.
Three tools to have before the first showing
None of these replaces a licensed home inspection, and none changes how a contract works. They help a buyer walk a house with better information during the short window that competitive listings allow.
- The Klein Tools RT210 Outlet Tester plugs into standard and GFCI outlets and flags common wiring faults such as open grounds or reversed polarity. See it on Amazon (affiliate link)
- The BOSCH GLM20 Blaze 65ft Laser Distance Measure checks room dimensions against a listing sheet and helps with furniture planning before an offer. See it on Amazon (affiliate link)
- The Epson Workforce ES-50 Portable Sheet-Fed Document Scanner turns preapproval letters, proof of funds and signed forms into PDFs quickly enough to meet a same-day deadline. See it on Amazon (affiliate link)
As an Amazon Associate I earn from qualifying purchases. A commission may be earned if you buy through this link, at no extra cost to you.
Questions buyers ask
Does a higher offer always win? No. The Close and SoFi both describe sellers who weigh closing dates, financing strength and contingencies alongside price.
How much is the deposit on a Long Island purchase? Nolo describes a contract deposit of typically 10% of the price, held in an attorney escrow account. National advice that cites 1% to 3% refers to a different convention.
Is an escalation clause a good idea? It can raise an offer automatically up to a stated limit, according to SoFi, but it also commits the buyer to a final price in advance. A buyer’s attorney should review the wording before it is used.
Should a buyer write a letter to the seller? NAR’s guidance describes fair housing risks, so the safer course is to let the financial terms speak.
Where does an appraisal gap come in? When the appraisal lands under the contract price, the buyer may owe the difference in cash, which is why a gap clause and a cash reserve belong in the ceiling.
This is for informational purposes only — consult a licensed attorney or financial advisor for your specific situation. Market figures reflect the sources and dates cited and may have changed since this post was written.
Real estate markets change. For current listings and market data, contact Maison Pawli at maisonpawli.com/about/.
You Might Also Like
- The Appraisal Gap Addendum Is a Negotiating Instrument, Not a Buyer Concession
- Earnest Money Is Not a Deposit: The Legal Distinction That Determines Who Keeps It
- The Inspection Report as a Negotiating Document
- The Science of Why We Overpay for Houses — And How to Stop
Sources
- Redfin, “NYC Suburbs and the Bay Area Are This Spring’s Most Competitive Housing Markets” (June 23, 2026): https://www.redfin.com/news/?p=86194
- Long Island Guide, OneKey MLS August 2026 data (Sept. 29, 2026): https://www.longislandguide.com/2026/09/29/long-island-housing-market-pushes-higher-as-nassau-and-suffolk-prices-rise-despite-slower-sales-limited-inventory/
- Freddie Mac, Primary Mortgage Market Survey (Oct. 8, 2026 reading): https://www.freddiemac.com/pmms
- Nolo, New York home buyers: what it means to be “in contract” (updated Aug. 14, 2023): https://www.nolo.com/legal-encyclopedia/new-york-home-buyers-what-does-it-mean-be-in-contract-what-happens-your-downpayment.html
- SoFi Learn, “How to Win a Bidding War” (Apr. 29, 2026): https://www.sofi.com/learn/content/real-estate-bidding-war/
- The Close, “How to Win a Bidding War on a House: 10 Tips for Success” (updated June 20, 2025): https://theclose.com/how-to-win-bidding-wars-tips/
- National Association of REALTORS®, “How to Handle Buyer Love Letters”: https://www.nar.realtor/magazine/broker-news/network/how-to-handle-buyer-love-letters
- Daily Press Tribune, “How to win a bidding war on an in-demand house, according to real-estate mogul Barbara Corcoran” (May 31, 2023): https://business.dptribune.com/dptribune/news/read/43402714/how_to_win_a_bidding_war_on_an_in