Co-op or Condo in New York? Seven Tests That Settle It
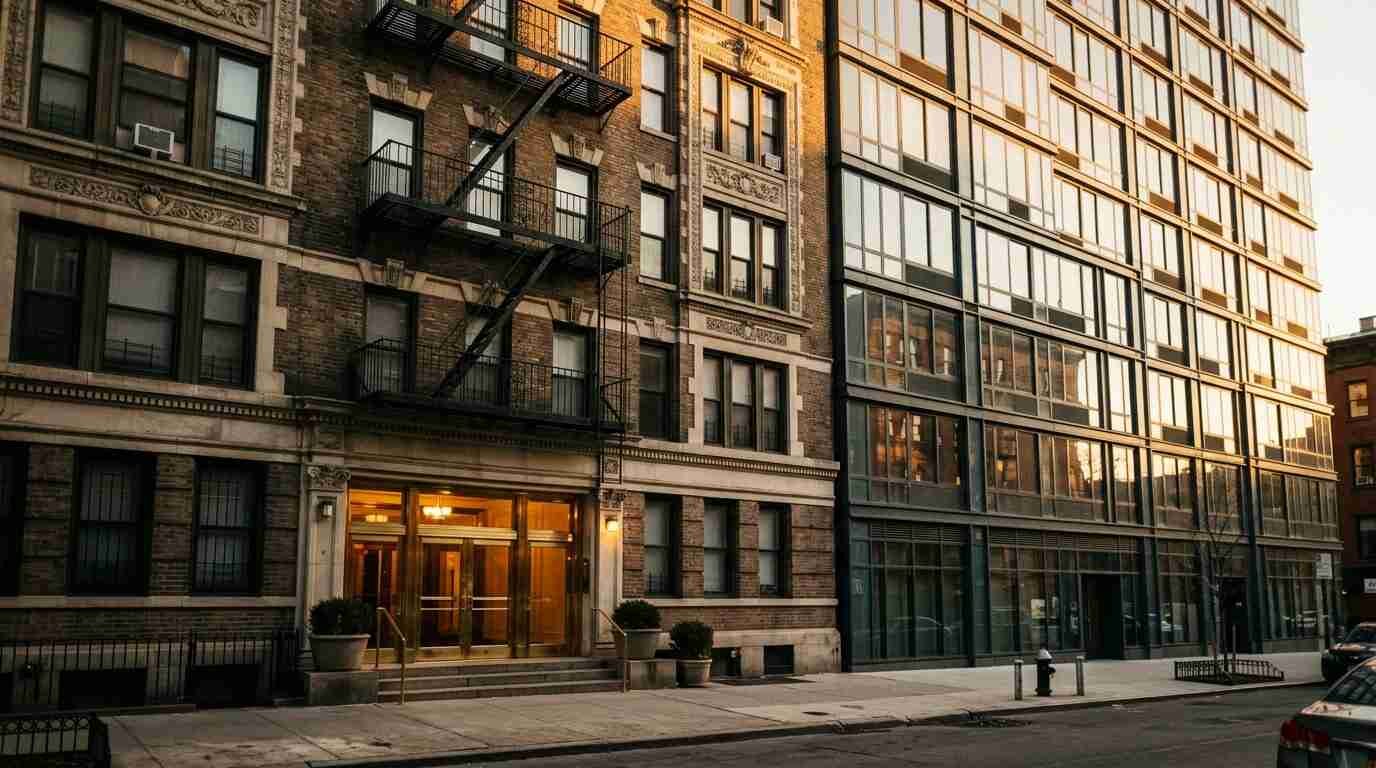
Starting July 28, 2026, a New York City co-op board that sits on a buyer’s application has a clock running against it. Local Law 58 of 2026 (Int. 1120-B) requires boards or their managing agents to confirm within 15 days whether a package is complete, then answer within 45 days of that confirmation, with a single extension of up to 14 days. For anyone weighing a co-op against a condo, that is the first real change to the approval process in decades, and it makes a good moment to rebuild the decision from scratch.
Most comparisons stop at a definition: co-op buyers own shares, condo buyers own real property. True, and rarely decisive. The choice usually turns on how a specific buyer’s finances, timeline, and plans line up against a specific building. Seven tests, applied in order, turn the question into something answerable.
What the new timeline law does, and what it does not
According to Brick Underground’s coverage of the law, boards must acknowledge an application by email and registered mail within 15 days. If no acknowledgment arrives in that window, the application is treated as complete. The law also requires co-ops to offer a standardized application, with forms, questionnaires, a list of sale requirements, and submission instructions.
Exemptions matter. The law does not cover HDFC or Mitchell-Lama co-ops, buildings with fewer than ten apartments, or condominiums, where the board’s power is a right of first refusal rather than an approval vote. Fox Rothschild partner Peter Massa told the publication, “This is a change that boards are paying attention to,” while noting that management companies face a heavy burden on applications that can run hundreds of pages.
One limit is worth stating plainly. The coverage reviewed for this post describes deadlines and standard forms. It does not describe a duty to explain a rejection. A Habitat magazine report from April 2026 notes that bills requiring reasons have not advanced in the City Council, and that Westchester County does require a stated reason. Anyone relying on a specific provision should confirm the current text with an attorney.
Test 1: The calendar test
Start with the date that cannot move. A lease ending in 60 days, a mortgage rate lock, or a school-year deadline all put a ceiling on how long an approval process can run.
Condos generally clear faster, because the board’s role is limited to deciding whether to exercise a right of first refusal, and most decline. Co-ops add an application package, financial documentation, and often an in-person interview. Under the new city timeline, the outer boundary is now knowable: 15 days to acknowledge, 45 to decide, plus a possible 14. Roughly two and a half months from submission to answer is the worst case on paper, not counting the weeks spent assembling the package.
A buyer who needs certainty in under a month is better matched to a condo. A buyer with flexibility can treat a co-op’s process as a manageable step rather than a barrier.
Test 2: The cash test
Cash requirements differ more than anything else on this list.
Many co-op boards set minimums for the down payment and for liquid assets left after closing, and some buildings expect more than lenders do. StreetEasy’s co-op and condo guide outlines these norms, which vary by building and change over time, so any figure should come from the building’s own application materials rather than a rule of thumb.
Closing costs tilt the other way. A condo buyer who finances usually pays mortgage recording tax in New York City, which Brick Underground explains in detail. A co-op loan is secured by shares rather than a recorded mortgage, so that tax generally does not apply. On a large loan, the difference can offset part of a higher down payment requirement. The state’s “mansion tax” on purchases of $1 million and up applies to both property types; the 2026 budget changes to second-home taxation are covered separately.
The cash test question: after the down payment, closing costs, and any required reserves, how much liquid money remains, and does it meet the building’s stated minimum?
Test 3: The approval test
Both structures give a board a gate. The width of the gate is the difference.
At a co-op, the board votes on the buyer. New York courts defer to board decisions under the business judgment rule, which is why boards rarely have to explain a “no.” They cannot, however, reject an applicant for reasons prohibited by federal, state, or city fair housing law. The attorneys at Belkin Burden Goldman, in a July 2026 legal brief, stress consistency in how boards process applications.
At a condo, the board can only match the buyer’s contract and buy the unit itself, and it seldom does. A buyer whose finances are unconventional, such as self-employment income, a recent job change, a gift from a relative, or an LLC purchase, usually faces fewer hurdles at a condo.
Long Island adds a wrinkle for anyone searching both sides of the city line. Suffolk County has a co-op admissions disclosure law, and the Village of Hempstead has an anti-discrimination co-op law, both of which differ from the city’s. Maison Pawli’s condo, co-op, and townhouse guide for Long Island buyers covers those local mechanics.
Test 4: The monthly bill test
Monthly charges are not directly comparable, and the common mistake is to compare a co-op’s maintenance against a condo’s common charges alone.
Co-op maintenance often folds in the building’s underlying property tax and, in many buildings, heat, water, and the share of any blanket mortgage. Condo owners pay common charges and then a separate property tax bill on their own unit. Lining up the two means adding the condo’s tax to its common charges and comparing the sum with the co-op’s maintenance.
Ask for the building’s financial statements, the reserve fund balance, and any pending or recent assessments. A low monthly figure on a building with thin reserves is often a bill deferred rather than a bill avoided. A guide to the cost of Long Island property taxes for buyers coming from the city helps with the same comparison on the suburban side.
Test 5: The rules test
Condos tend to allow more flexibility on subletting and renting out the unit, subject to the building’s governing documents. Co-ops frequently limit or prohibit sublets, cap the number of years an owner may sublet, or require board consent each time. Pet policies, renovation approvals, and pied-à-terre or non-primary-residence rules vary on both sides.
For someone who may relocate for work, or who wants the option to rent the apartment for a stretch, the rules test can outweigh price. Read the proprietary lease or condo declaration and house rules before signing a contract, not after.
Test 6: The lender test
Financing narrows the field. Condo loans are generally underwritten against the building as well as the borrower, and the lender may apply project standards. Fannie Mae’s Selling Guide publishes the project requirements its loans use, which include limits tied to owner-occupancy and the financial condition of the association. Co-op lenders look at the corporation’s finances and the share-loan structure. Not every lender handles every building.
Getting pre-approved by a lender experienced with the property type, before touring, avoids discovering a building problem after an offer is accepted. For current rate conditions, see this fall’s mortgage rate update and the overview of mortgage options for first-time buyers.
Test 7: The exit test
The final test asks what happens at resale. A condo can be sold to almost any qualified buyer, which widens the buyer pool. A co-op sale carries the same board review the seller once went through, which narrows the pool and can lengthen the timeline.
Co-ops also commonly charge a flip tax on sale, set by the building. Habitat magazine’s guide to flip taxes describes how those fees are structured. Check whether a building has one, who pays it, and how it is calculated. Anyone planning to hold the apartment for fewer than five years should weigh this test more heavily than the others.
Scoring the seven tests
| Test | Often favors a condo when… | Often favors a co-op when… |
|---|---|---|
| Calendar | The closing date is fixed and tight | There is room for a 45-to-60-day approval |
| Cash | Down payment is smaller than co-op minimums | Closing costs matter more than down payment |
| Approval | Income or funds are unconventional | Finances document cleanly |
| Monthly bill | Condo charges plus tax come in lower | Maintenance includes heat, taxes, and services |
| Rules | Renting out or subletting may be needed | The owner plans to live in the unit long term |
| Lender | A lender approves the condo project | The co-op’s finances are strong |
| Exit | Resale in a few years is likely | The hold period is long |
Four or more checks in one column point to a direction. A split result is a signal to ask an attorney and a lender to review a specific building rather than a property type.
Questions buyers ask
Is a co-op always cheaper than a condo?
Not always. Purchase prices for comparable apartments are often lower in co-ops, but maintenance, assessments, and the flip tax can narrow the gap. Compare total monthly and exit costs, not asking prices.
Does the new city law let a buyer find out why a board said no?
The coverage reviewed for this post describes timelines and standardized applications, not a requirement to explain a rejection. Confirm the current law with an attorney.
Can a condo board block a sale?
Only by exercising a right of first refusal, which boards rarely use. The mechanics resemble those in the HOA right-of-first-refusal guide.
Does the same analysis apply on Long Island?
The framework does. The local rules differ, and the property tax and insurance pictures differ too; see the guides on homeowners insurance before an offer and the STAR exemption.
Tools for the apartment hunt
Paperwork piles up fast during a co-op application, and a few practical items help during showings and diligence.
- Nolo’s Essential Guide to Buying Your First Home explains the purchase process in plain terms. See it on Amazon (affiliate link)
- The Fujitsu ScanSnap iX1600 document scanner digitizes the application package, tax returns, and statements into searchable files. See it on Amazon (affiliate link)
- The Klein Tools RT210 GFCI receptacle tester gives a quick read on outlet wiring during a walk-through, though it does not replace a licensed inspection. See it on Amazon (affiliate link)
As an Amazon Associate I earn from qualifying purchases. A commission may be earned if you buy through this link, at no extra cost to you.
This is for informational purposes only — consult a licensed attorney or financial advisor.
Real estate markets change. For current listings and market data, contact Maison Pawli at maisonpawli.com/about/.
You Might Also Like
- Closing Costs on Long Island: A Buyer’s Breakdown
- How to Read a Title Commitment and Chain of Title
- Guide to Buying a Home on Long Island’s North Shore
Sources
- Brick Underground: Co-op boards’ new timeline to approve or reject applications
- NYC Council Legistar, Int. 1120
- Fox Rothschild: New York City cooperatives face new timelines for reviewing purchase applications
- Habitat: Co-op board buyer rejection process (April 2026)
- Belkin Burden Goldman: The legal limits of co-op board rejection
- StreetEasy: Co-ops vs. condos, NYC home buyer’s guide
- Brick Underground: Mortgage recording tax in NYC
- Fannie Mae Selling Guide: Project standards
- Habitat: Flip taxes in NYC co-ops
- Habitat: Co-op admissions, new Suffolk disclosure law
- LIBOR: Village of Hempstead anti-discrimination co-op law