What Closing Costs Actually Look Like on Long Island
Long Island buyers should expect 2–5% of the purchase price in closing costs. Here’s the line-by-line breakdown with real numbers for Suffolk and Nassau.
Long Island buyers should expect 2–5% of the purchase price in closing costs. Here’s the line-by-line breakdown with real numbers for Suffolk and Nassau.
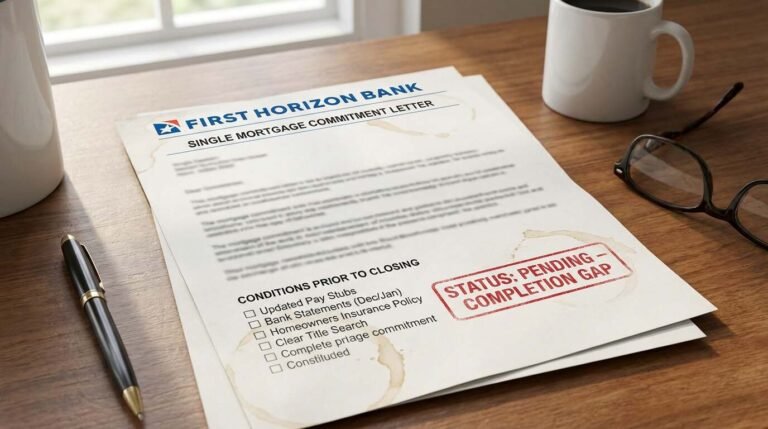
A mortgage commitment letter is a conditional promise, not a binding loan approval. The conditions it contains are the legal fault lines where transactions fail.
Suffolk County’s top school districts drive home prices $50–$100 more per square foot. Here’s which districts rank highest and what that means for buyers.
Post-war deed restrictions in Nassau and Suffolk County can void FHA loan approvals for first-time buyers. Here’s what to look for — and how to protect yourself.
Hauppauge homes hold value unlike almost anywhere on Long Island. The reason isn’t just test scores — it’s a deliberate zoning structure engineered decades ago.
A Cold Spring Harbor spec home closed well above ask while the custom build next door sat for months. The difference wasn’t price. It was certainty. Here’s what that means for buyers now.
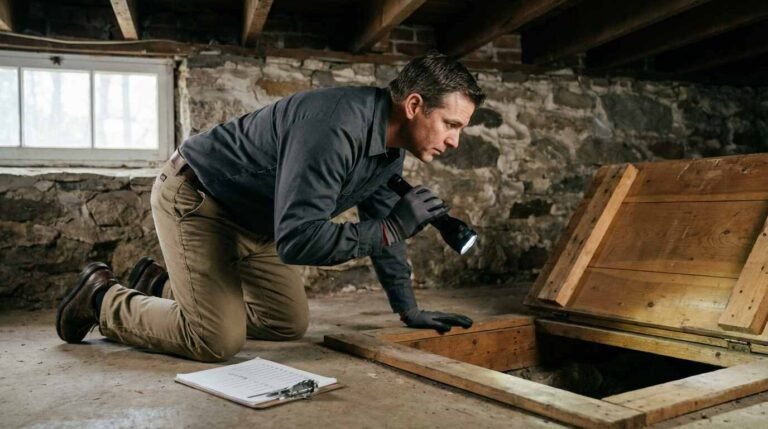
Waiving your inspection contingency to win a bid feels strategic. The legal exposure it creates is real and documented. Here’s what you need to know before you sign.
Suffolk County’s HOME-funded down payment assistance programs are real and valuable — but they come with timing risks most buyers don’t know about. Here’s what to ask before you apply.
HUD’s 203(k) loan lets buyers finance a home and its renovation in a single mortgage. Lender complexity keeps most from mentioning it. Here’s what it actually covers.
A buyer who misses the contingency removal deadline has either waived the contingency or handed the seller the right to cancel — depending on which state they’re in.