Fed Minutes Point to Another Hike by Year-End
The Federal Reserve raised its policy rate by a quarter point on September 16, to a range of 3.75% to 4%, its first increase since July 2023, as Mortgage Professional America reported. Minutes released on October 7 show how divided and how determined officials were, according to the Scotsman Guide. For borrowers, the minutes matter less for what they say about the fed funds rate than for what they imply about the direction of long-term borrowing costs.
A rate increase after a long pause shifts the conversation for homebuyers, homeowners considering a refinance and sellers weighing whether to list. It also raises a common question: does a Fed hike push mortgage rates up directly? The answer is more complicated than the headlines suggest, and the minutes offer some of the clearest evidence of why.
What the minutes show
- Most participants judged another hike by year-end likely appropriate.
- Some viewed the September move as risk management against persistent inflation.
- Several described the policy rate as not restrictive or only mildly restrictive.
- Sixteen of 18 policymakers projected at least one more hike in 2026, per MPA.
Taken together, those points describe a committee that sees inflation as the larger danger and is prepared to keep tightening to contain it. Calling the policy rate only mildly restrictive is notable, because it implies officials believe more room exists before the economy slows meaningfully. The CNBC International segment above reports that the minutes reduced the odds of an October increase, which illustrates how markets weigh the timing separately from the direction.
The October meeting
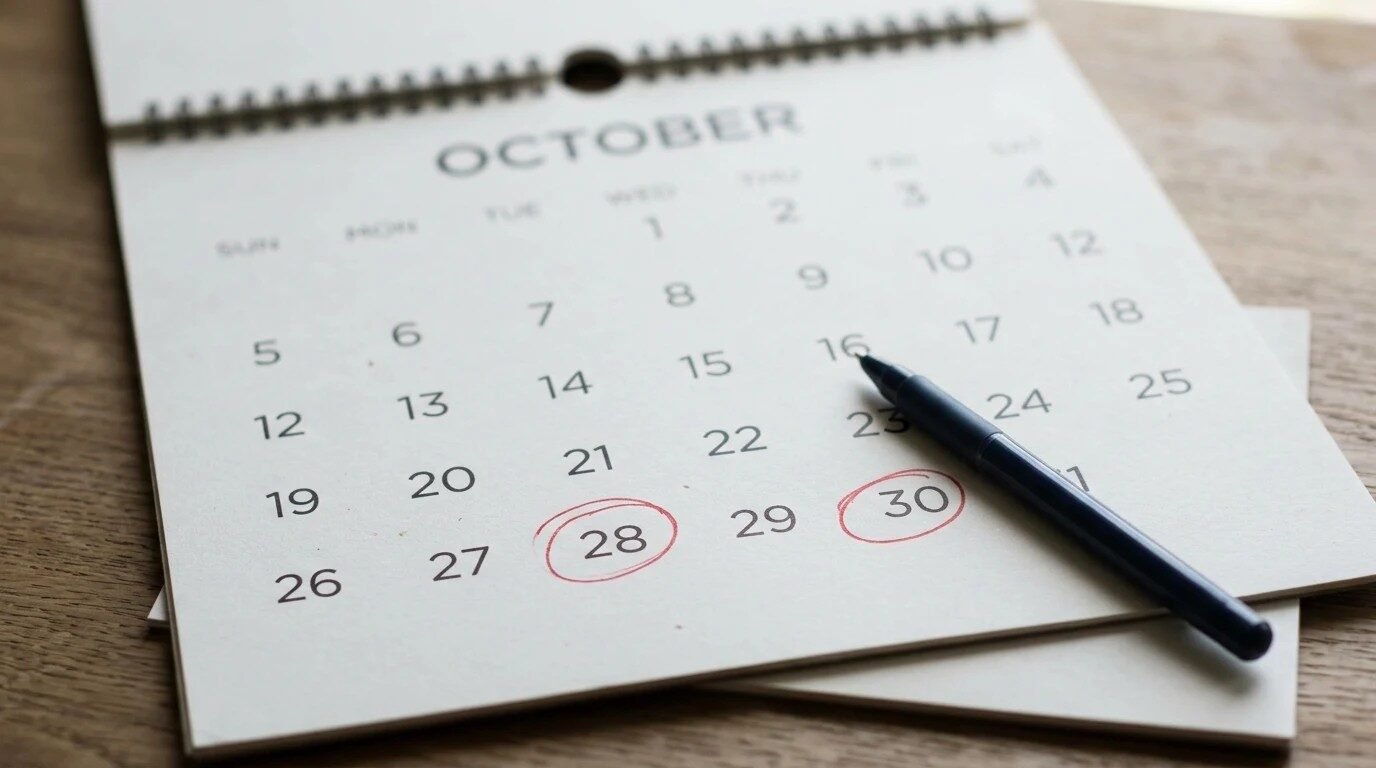
The next meeting concludes October 28. CME FedWatch put the odds of an October hike at about 77.5% on September 24, but only 17% as of October 7, with 84% for December. Expectations shifted within two weeks, and the minutes and a weak jobs report both landed in that window. Such rapid changes in market odds are a reminder that forecasts of Fed action are probabilities, not promises.
What it does to mortgage rates
Fixed mortgage rates follow the 10-year Treasury yield more than the fed funds rate. Melissa Cohn of William Raveis Mortgage noted that mortgage rates rose in 2025 even as the Fed was cutting, and Lisa Sturtevant of Bright MLS said the hike makes rates at or above 7% likely. Both views can be right: the policy rate is one input and the bond market’s expectations about inflation are another. When investors expect the Fed to fall short of its inflation goal, long-term yields can rise even if short-term rates stay put.
That dynamic explains why borrowers sometimes see mortgage quotes move before the Fed does anything at all. By the time of an announcement, the bond market has usually priced in most of the expected change, so the surprise element, and therefore the rate reaction, depends on how the decision compares with expectations.
Practical steps for borrowers
Borrowers with a closing coming up can ask a lender about locking a rate, which fixes the quote for a set period, sometimes for a fee and sometimes at a stated cost. Terms vary by lender, so the details belong in writing. Those still shopping can compare quotes from several lenders on the same day, since rates differ even when the market is calm, and the weekly Freddie Mac survey provides a neutral benchmark for judging whether a quote is competitive.
More detail on current quotes is in the post on the Treasury yield and loan types, and the payment effect of different loan terms appears in the 15-year versus 30-year comparison.
This article reports published figures for general information. It is not financial, legal or lending advice, and every number reflects the date of its source, so confirm current figures before acting on them.